Laplace Flood Claims Lawyer
Schedule a free consultation with an experienced Laplace, LA flood claims lawyer today.
If your home or business in Laplace sustained flood damage and your insurance company has denied your claim, delayed payment, or offered far less than the damage warrants, a Laplace, LA flood claims lawyer at Kiefer & Kiefer can help you pursue the full amount you are owed.
Our firm has over 40 years of experience representing policyholders in hurricane and insurance claims throughout southeastern Louisiana, including flood damage disputes arising from Hurricane Ida. We handle every case on a contingency fee basis, so you pay nothing unless we recover compensation for you.
Flood Claims Lawyer Laplace, LA
Laplace sits between Lake Pontchartrain and the Mississippi River in St. John the Baptist Parish, a geographic position that makes it particularly vulnerable to flooding during hurricanes and heavy rain events. Hurricane Ida in August 2021 brought 17 inches of rain and up to 5 feet of storm surge to the parish, damaging the majority of structures in the area. Many of the insurance claims filed in the aftermath were underpaid, delayed, or denied.
A flood claim is a dispute between a policyholder and an insurance company over the amount owed for flood-related property damage. These claims may involve the National Flood Insurance Program, a private flood policy, a homeowner’s policy, or a combination of these. The legal strategy depends on the type of policy, the source of the damage, and the insurer’s conduct.
Types of Flood Claims Cases We Handle in Laplace
Flood damage disputes involve a range of issues depending on the type of property, the insurance coverage in place, and the cause of the loss. Our attorneys handle flood claims in Laplace, LA involving the following situations.
- Homeowner insurance claims. Standard homeowner policies in Louisiana often exclude flood damage but may cover water intrusion from wind-driven rain or roof damage. Disputes over what the policy does and does not cover are among the most common insurance claim issues following a storm.
- Hurricane damage claims. Hurricanes cause damage from wind, rain, storm surge, and flooding, and insurers frequently try to attribute damage to the peril that carries the least coverage. Preparing for a hurricane claim before the storm hits can strengthen your position, but even after the fact, a thorough investigation of the damage and the policy language can change the outcome.
- Wind versus water disputes. After a hurricane, one of the most contested issues is whether the damage was caused by wind, which a homeowner’s policy may cover, or by floodwater, which typically requires a separate flood policy. Insurers use this distinction to minimize their exposure. We retain independent adjusters and engineers to assess the damage and identify the actual cause.
- Underpayment and low appraisals. An insurer may acknowledge coverage but issue a payment that falls well short of what the repairs actually cost. This happens when the insurer’s adjuster underestimates the scope of damage, applies depreciation incorrectly, or excludes items that should be covered. We review the insurer’s estimate against independent repair assessments to identify the gap.
- Denied flood claims. A claim denial does not necessarily end the process. Insurers deny claims for a range of reasons, and not all of those reasons hold up under the policy language or Louisiana law. Common grounds include allegations that the damage was preexisting, that the policyholder failed to provide adequate proof of loss, or that the claimed damage falls outside the policy’s covered perils. We evaluate whether the denial is supportable and advise you on the options available.
- Bad faith insurance practices. Louisiana law requires insurers to adjust claims fairly, respond within specific timeframes, and pay amounts due promptly. When an insurer fails to meet these obligations, the policyholder may be entitled to penalties and attorney fees in addition to the unpaid policy benefits. Our firm has obtained bad faith penalty awards against insurers in hurricane-related disputes, including claims arising from Hurricane Ida.
- Commercial property flood claims. Businesses in Laplace that suffered flood damage may have claims under commercial property policies, business interruption coverage, or both. The losses in these cases extend beyond the physical damage to include lost revenue, displacement costs, and inventory losses.
Why Choose Kiefer & Kiefer as My Flood Claims Lawyer in Laplace, LA?
Local Knowledge, Insurance Claim Results
Kiefer & Kiefer is not a firm that handles flood claims from a distance. We serve clients in Laplace and throughout St. John the Baptist Parish, and we understand the specific flooding risks, storm patterns, and insurance coverage issues that affect this area. Our attorneys have represented homeowners and businesses in flood damage disputes following Hurricane Ida and other storms, and we have recovered millions of dollars for policyholders whose claims were underpaid or denied.
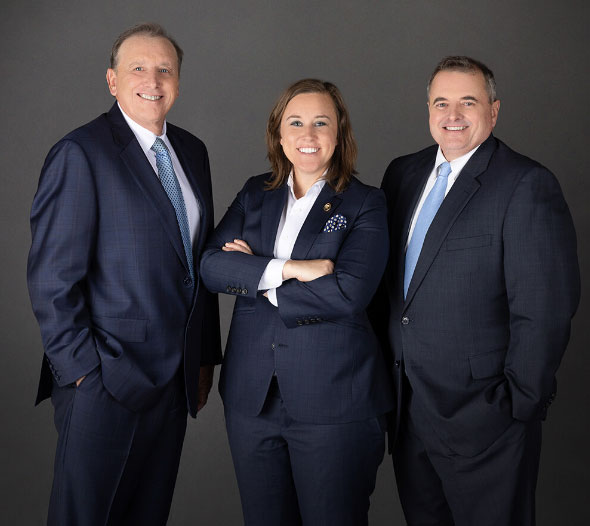
Megan Kiefer is a partner at the firm who graduated from Tulane University Law School with Order of the Coif distinction. She has been named a Super Lawyers honoree across multiple years and was inducted into the Multi-Million Dollar Advocates Forum. She also serves on the adjunct faculty at Tulane, where she teaches Trial Advocacy, and she has completed advanced mediation and negotiation training at Humboldt University of Berlin.
Nat Kiefer Jr. graduated with honors from Tulane University Law School in 1982 and received the Walter Sutton Award. He has practiced law in Louisiana for over 40 years and has handled insurance disputes, property damage claims, and personal injury cases across the state’s courts. Chris Short is a partner who graduated magna cum laude from Tulane University Law School. He is licensed in Louisiana and Florida, and his background includes a degree from California State University Maritime Academy.
Kiefer & Kiefer also serves as a personal injury lawyer in Laplace, LA and handles flood and insurance claims on a contingency basis. You owe nothing unless we recover for you.
What Is Important to Understand About a Flood Claims Case?
Recovery, Bad Faith Penalties, and Policyholder Rights
When an insurer fails to pay a valid flood claim or significantly underpays the damage, Louisiana law provides remedies beyond the unpaid policy benefits. Under Louisiana Civil Code Article 2315, a person or entity that causes damage through fault is obligated to repair it, and this principle extends to insurers whose bad faith conduct causes economic harm to their policyholders.
Louisiana’s insurance statutes require insurers to initiate loss adjustment within 14 days of receiving notice of a claim and to issue payment within 30 days of receiving satisfactory proof of loss. For catastrophic losses like those caused by a hurricane, the timelines are somewhat longer, and Louisiana law now requires a written cure period notice before a bad faith lawsuit can be filed. When an insurer’s failure to pay is found to be arbitrary, capricious, or without probable cause, the policyholder may recover penalties of up to 50% of the amount due, along with proven economic damages and attorney fees.
What Are Important Aspects of a Flood Claims Case?
Flood claims involve issues that standard property damage cases do not. The most common points of dispute include the following.
- The source of the damage is frequently contested. After a hurricane, an insurer may argue that the damage was caused by flooding rather than wind, which shifts the claim from the homeowner’s policy to the flood policy or eliminates coverage altogether. Independent engineering assessments and damage inspections are often necessary to establish which peril caused which portion of the loss.
- Documentation is critical from the start. Policyholders should photograph and video the damage as soon as it is safe to do so, keep records of any temporary repairs, save receipts for displacement costs, and document the process of filing a claim with the insurer. A detailed proof of loss is required, and errors or omissions in the proof of loss can be used by the insurer to delay or deny payment.
- Louisiana’s comparative fault law under Civil Code Article 2323 generally applies to tort claims, including bad faith claims against insurers. And the general prescriptive period for filing a lawsuit related to an insurance dispute is governed by Civil Code Article 3493.1, which provides a two-year period for delictual actions arising after July 1, 2024.
- Policyholders who are unsure whether they need an attorney to handle a hurricane-related insurance dispute should consult with a lawyer before accepting a settlement offer or signing a release.
What Is the Flood Claims Case Timeline?
The timeline of a flood claim depends on the insurer’s response, the complexity of the damage, and whether the claim moves into litigation.
- After reporting the loss, the insurer should send an adjuster to inspect the property. Louisiana law requires this process to begin within 14 days of notice, or within 30 days for catastrophic losses.
- Once the inspection is complete, the insurer must issue a coverage determination and, if the claim is covered, make payment within the statutory timeframe.
- If the payment is inadequate, or if coverage is denied, the dispute enters a negotiation phase. For catastrophic losses, policyholders must now provide a written cure period notice and allow the insurer 60 days to respond before filing suit.
- If the dispute cannot be resolved, we file a lawsuit on your behalf. The litigation process involves discovery, depositions, and potentially trial.
Throughout, we retain independent adjusters, contractors, and engineers to document the actual cost of repairs and counter the insurer’s estimates.
What Should You Bring to Your Flood Claims Consultation?
The more documentation you can bring, the faster we can evaluate your claim. Useful materials include:
- Your insurance policy and any endorsements or amendments
- The insurer’s written coverage determination or denial letter
- The adjuster’s damage estimate
- Photographs and video of the property damage
- Receipts for any temporary repairs or displacement costs
- Any correspondence with the insurer
If you do not have all of these materials, we can begin with what is available. Many policyholders contact us before the claims process is complete, and we can step in at any point to protect your interests.
What Are Important Louisiana Legal Resources for Flood Claims Cases?
Flood claims in Louisiana are governed by a combination of state insurance statutes, federal flood insurance regulations, and general tort law. If you are researching the laws that apply to your situation, the resources below provide a useful starting point.
- FEMA National Flood Insurance Program: Administers the federal flood insurance program through which most residential flood policies in Louisiana are written.
- Louisiana Department of Insurance: Regulates insurance carriers operating in the state and provides resources for filing complaints.
- Civil Code Articles: Louisiana’s general negligence and damages framework is established in the state’s governing obligations arising from fault.
- Civil Code Article 3493.1: The prescriptive period for filing a bad faith lawsuit provides a two-year window for delictual actions arising after July 1, 2024.
Reach Out to Kiefer & Kiefer to Schedule a Consultation
If your flood claim in Laplace has been denied, delayed, or underpaid, Kiefer & Kiefer can review your policy and the insurer’s response and advise you on the best path forward. We represent policyholders on a contingency basis, so there are no upfront costs and no attorney fees unless we recover compensation for you. Contact us to schedule a free consultation.
Flood Claims Statistics in Laplace
 St. John the Baptist Parish sits on low ground between Lake Pontchartrain and the Mississippi River, which means water arrives from more than one direction and drains slowly once it does. Homeowners in Laplace have learned that the question after a storm is rarely whether the property took on water. It is whether the carrier will pay what the policy promised, and how long the argument will take.
Federal flood data helps explain why so many claims end in dispute. The cost of even shallow flooding runs far higher than most policyholders expect, and a substantial share of losses occur in places the maps do not classify as high risk. The figures below come from FEMA and the National Flood Insurance Program.
- FEMA reports that just one inch of water can cause roughly $25,000 in damage to a property.
- Ninety-nine percent of U.S. counties have experienced a flood since 1998.
- More than 40 percent of flood insurance claims are filed for properties located outside designated high-risk flood areas.
- Between 2016 and 2022, the average FEMA disaster assistance grant was $3,000, while the average NFIP claim payment exceeded $66,000.
- FEMA publishes the full NFIP claims history dating to 1978 through its public data platform, refreshed on a rolling basis.
Mistakes That Can Damage Your Flood Claim
A valid flood claim can still be reduced or denied because of a missed deadline or an incomplete submission. The mistakes below come up regularly, and most of them are avoidable once a policyholder knows to watch for them.
- Cleaning up before the damage is documented. The instinct to gut wet drywall and haul out ruined furniture is understandable, and mitigation is required by most policies. But photograph and video everything first, including water lines on the walls, saturated flooring, and the interior of cabinets. Once the material is gone, the carrier’s adjuster has only your word for what was there.
- Throwing away receipts. Temporary repairs, dehumidifier rentals, hotel stays, and replacement clothing are frequently recoverable. Policyholders who discard receipts effectively waive the reimbursement.
- Missing the proof of loss deadline. Flood policies impose strict timelines for submitting a sworn proof of loss. An incomplete or late submission gives the carrier a procedural basis to deny payment without ever reaching the question of what the damage actually cost.
- Accepting the adjuster’s estimate as final. The adjuster works for the insurance company. Their estimate is a starting position, not a binding valuation, and independent contractor pricing frequently comes in substantially higher.
- Signing a release to get a quick check. Cashing a settlement check accompanied by a release can close the claim permanently. Damage that surfaces later, including mold and structural movement, may no longer be recoverable.
- Giving a recorded statement without preparation. Carriers ask about prior damage, prior claims, maintenance history, and when the water entered. Casual answers to those questions get used later to support a preexisting damage defense.
- Assuming the denial letter is the end. Denials are issued for reasons that do not always hold up under the policy language or Louisiana law. Preexisting damage, late notice, and inadequate proof of loss are the common grounds, and each can be challenged with the right evidence.
- Failing to separate wind damage from water damage. When a storm brings both, carriers on each side of the coverage line have an incentive to point at the other peril. An engineering assessment that assigns damage to its actual cause is often what breaks the stalemate.
- Waiting too long to involve counsel. Louisiana imposes notice requirements before certain bad faith suits can be filed, and evidence of the damage degrades as repairs proceed. Early involvement preserves options that later involvement cannot recover.
Laplace Flood Claims Lawyer FAQs
What does it cost to hire a flood claims attorney?
We handle these matters on a contingency fee. There is no retainer and no hourly billing, and no attorney fee is owed unless we recover money for you. In successful bad faith claims, Louisiana law also allows recovery of attorney fees from the carrier, which can reduce the cost of representation further.
My claim was denied. Is that the end of it?
No. A denial reflects the carrier’s position, not a legal ruling. We review the policy language, the adjuster’s report, and the stated grounds for denial to determine whether the position is supportable. Many denials rest on assumptions about preexisting damage that an independent inspection can disprove.
How is a flood policy different from my homeowner policy?
Most homeowner policies in Louisiana exclude damage caused by rising water. Flood coverage generally has to be purchased separately, through the National Flood Insurance Program or a private carrier. Wind-driven rain entering through a damaged roof may fall under the homeowner policy, which is why the source of the water matters so much.
How long do I have to bring a claim against my insurer?
The deadline depends on whether the claim is contractual or arises from the carrier’s handling of it, and flood policies carry their own suit limitation provisions that can be considerably shorter than the general prescriptive periods under Louisiana law. Because these deadlines vary by policy, they should be reviewed as soon as a dispute develops.
What are bad faith penalties?
When a carrier’s refusal to pay is arbitrary, capricious, or without probable cause, Louisiana law allows recovery beyond the policy benefits themselves. That can include statutory penalties calculated on the amount owed, proven economic damages, and attorney fees. Establishing bad faith requires documenting both the amount due and the carrier’s conduct.
Should I hire my own adjuster?
Independent adjusters and contractors can be useful, particularly on larger losses where the carrier’s scope of damage is incomplete. We coordinate that work as part of the case and retain engineers when the cause of the damage is disputed rather than the amount.
Does filing a claim raise my rates or get me dropped?
Rate and renewal decisions are governed by state insurance regulation and the terms of your policy. Concern about renewal is understandable, but it is not a reason to accept an underpayment. The Louisiana Department of Insurance regulates carriers operating in the state and accepts policyholder complaints.
What if my business flooded rather than my home?
Commercial claims often involve more than structural repair. Business interruption coverage, extra expense coverage, and inventory losses can all be in play, and proving lost revenue usually requires financial records and sometimes forensic accounting.
Can I still recover if I did not have flood insurance?
Sometimes. Depending on the facts, a claim may lie under a homeowner policy for wind-driven water intrusion, or against a third party whose conduct caused or worsened the flooding. It is worth having the circumstances reviewed before assuming nothing is available.
What should I bring to the first meeting?
The declarations page and full policy, any denial or payment letter, the adjuster’s estimate, photographs, and receipts. If you do not have all of it, bring what you have. We can request the rest from the carrier directly.
Important Resources for Laplace Flood Claims Cases
What Are Important Local Resources for Laplace Flood Claims?
Flood recovery in St. John the Baptist Parish runs through several agencies, and knowing which office handles what saves time when a claim is already moving slowly.
- St. John the Baptist Parish Government, (985) 652-9569, administers permitting, floodplain management, and emergency preparedness for the parish.
- Louisiana Department of Insurance, (225) 342-5900, regulates carriers licensed in Louisiana and accepts complaints from policyholders about claim handling.
- FEMA National Flood Insurance Program publishes policy information, claims data, and records on properties with repeated flood losses.
- St. John the Baptist Parish Sheriff’s Office, (985) 652-9513, coordinates evacuation notices and public safety information during storm events.
These organizations appear here for the reader’s convenience. Kiefer & Kiefer does not endorse them, and none is affiliated with our firm.
About Kiefer & Kiefer
Kiefer & Kiefer has represented Louisiana policyholders in property and insurance disputes for more than forty years. Partner Nat G. Kiefer, Jr. served on the Moot Court Board at Tulane University Law School and earned his undergraduate degree there with honors in 1979 before beginning a Louisiana practice that has now spanned four decades. The firm pursues carriers that delay or underpay valid claims, including a recovery of $250,000 in bad faith penalties following Hurricane Ida.
What Our Clients Say
★★★★★
“Throughout the duration of our legal battles, Megan and everyone at Kiefer & Kiefer kept us informed, answered every question, and fought tirelessly on our behalf, ultimately securing us the best possible outcome. Megan has been such a relief and a reassurance throughout an extremely difficult time. Having Kiefer and Kiefer on your side when you need legal assistance is the smartest move you can make.” – Matthew G.
Read more reviews on our Google Business Profile.
Additional Resources for Laplace Flood Claims Cases
- How Do I Prepare for a Hurricane if I May Need to Make an Insurance Claim?
- How Do I Make an Insurance Claim for Storm Damage?
- How to Make an Insurance Claim When a Home Business Is Damaged
- How to Deal With Insurance Adjusters After a House Fire
Contact Kiefer & Kiefer
If your carrier has denied, delayed, or shortchanged a flood claim, a Laplace flood claims lawyer at Kiefer & Kiefer can read the policy against the adjuster’s report and tell you where the gap is. The initial case review costs nothing, and we take these matters on a contingency fee, so you owe no attorney fee unless we recover on your behalf. We can step in at any stage, including while the claim is still open with the carrier. Contact us to have your policy and the insurer’s response reviewed.
Free Consultation
Client Review
"Megan and her team are the absolute best. They are patient, professional and thorough. I have no doubt that my getting back to myself after the car accident was their priority. Megan encouraged me to stay the course, work through my treatments, trust my doctors and let her handle the rest. That’s exactly what I did and she DID NOT let me down. I, without a doubt would refer her to my family and friends."
Kelly Ellis